

A few weeks ago, Marco Bario texted his landlord with an unusual request.
Bario and his wife, Tracy Neill, rent a four-bedroom townhouse in Frederick County, Maryland, about an hour outside Washington, DC. When they got the place in June 2024, they felt lucky to find respite from a sizzling rental market. Recently, however, they’d noticed comparable rental homes in the area going for hundreds of dollars less — some landlords were even cutting asking rents in a desperate bid for tenants. With their lease renewal date fast approaching, Bario posed a simple question to his landlord: What would he consider a fair monthly rent for the next year?
The text kicked off a cordial but pointed back-and-forth. “You’ve been great tenants,” the landlord replied, but he felt the rent was “already within a fair range.” Bario persisted, noting that similar four-bedroom listings online were charging in the low $3000s — well below the $3,650 he and Neill were paying. After a few more exchanges over the ensuing week, the landlord sent a message with a new offer: he’d lower their rent to $3,375. A sharp eye and a handful of texts had saved the couple $275 a month.
“We like the relationship, but the market’s the market,” Bario tells me. “Why not ask?”
Such a request might have been met with a “😂” from a landlord just a couple of years ago. These days, though, many property owners are bracing for similar conversations. A historic wave of apartment construction, particularly in the lower half of the US, has put a lid on rent growth and shifted the balance of power in favor of tenants. Forced to compete with a glut of new units, property managers are more focused on keeping their buildings full than jacking up rents. It’s not uncommon for lease renewal offers to go out with no change to the monthly payment, a far cry from the days of double-digit percentage increases at the housing reshuffle’s peak. For prospective new tenants, landlords are doling out “concessions” like a month or two of free rent in hopes of getting them through the front door.
“It’s definitely a renter’s market right now,” says Caitlin Sugrue Walter, the head of research for the National Multifamily Housing Council.
This state of affairs won’t last long. Landlords are hustling to fill all those freshly built studios and one-bedrooms, betting they’ll be able to bring back the rent hikes later. They’re already looking ahead to next year, when developers are expected to deliver far fewer new units than during the 2024 peak.
For now, though, renters have a chance to flip the pandemic-era script. Landlords across the country no longer have free rein to lift prices and preside over rental bidding wars. Savvy tenants are embracing a time-worn mantra: If you don’t ask, you don’t get.
If you do manage to snag lower rent, there’s one group of people you should thank: builders.
Current rental trends are mainly a story about new supply. Apartment developers and homebuilders pay close attention to the shifting winds of the real estate market. They track how many people are moving, where they’re headed, and why, then try to adjust construction accordingly. Back in 2020 and 2021, the signals were obvious: build, build, build.
Coastal defectors were flocking to Sun Belt cities like Austin, Phoenix, and Denver, where they could get more bang for their buck than in, say, New York or San Francisco. Roommates were also striking out on their own, opting for studios or one-bedrooms instead of cramming into two- or three-bedrooms. Eager to meet the surge in demand, developers got busy. At the end of 2022, more than 971,000 apartment units were under construction, according to the real-estate software company RealPage, the second-largest number on record.
It’s definitely a renter’s market right now.Caitlin Sugrue Walter, head of research for the National Multifamily Housing Council
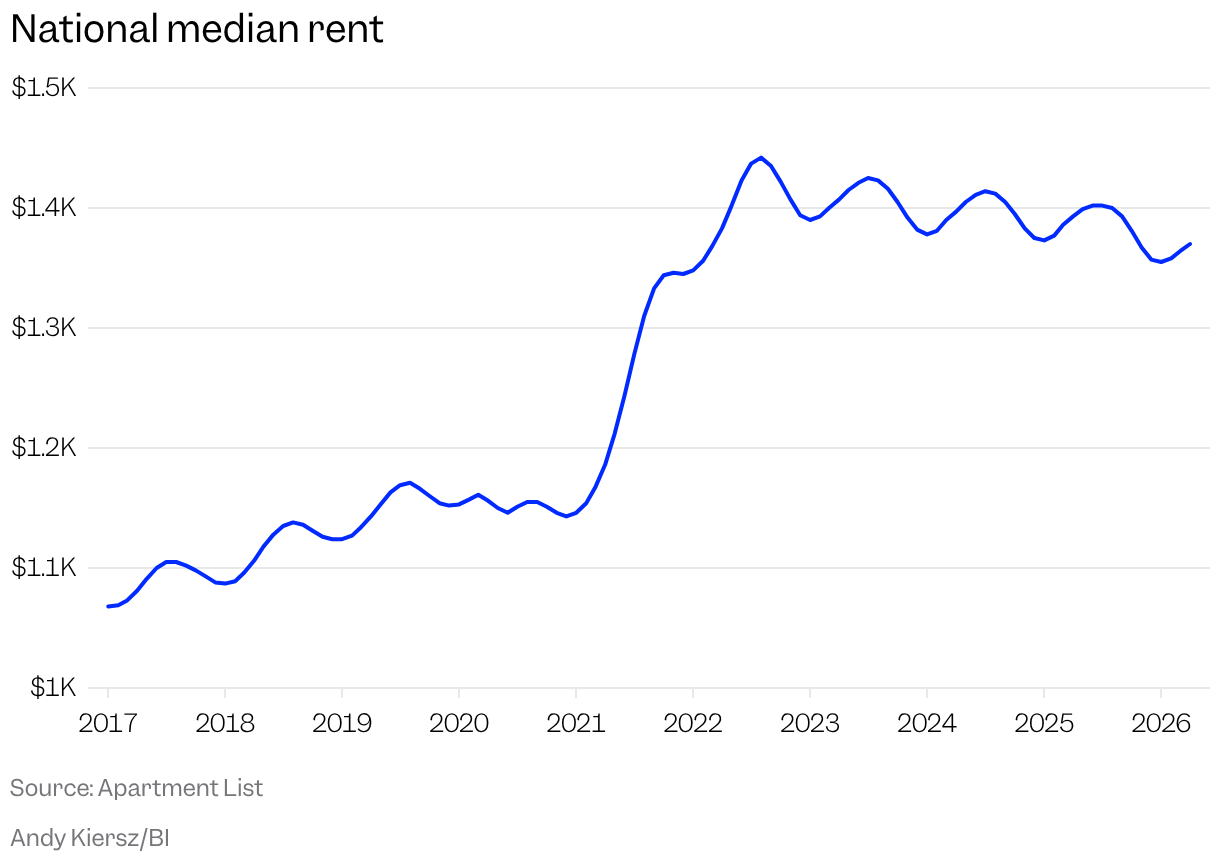
Even in the smoothest of scenarios, apartment construction typically takes a couple of years. This is why, despite all those bustling job sites, it didn’t feel like renters were getting any relief. Between 2020 and 2024, the typical rent nationwide jumped by nearly 30%, according to Zillow. Behind the scenes, though, a wave of new supply was about to upend the rental market. In 2024, more than 600,000 new multifamily units opened their doors — the most in a single year since the mid-1980s, according to an Apartment List analysis of Census data. Last year, developers wrapped construction on a little under 500,000 units.
“It really has been a pretty historic surge,” says Chris Salviati, the chief economist at Apartment List.
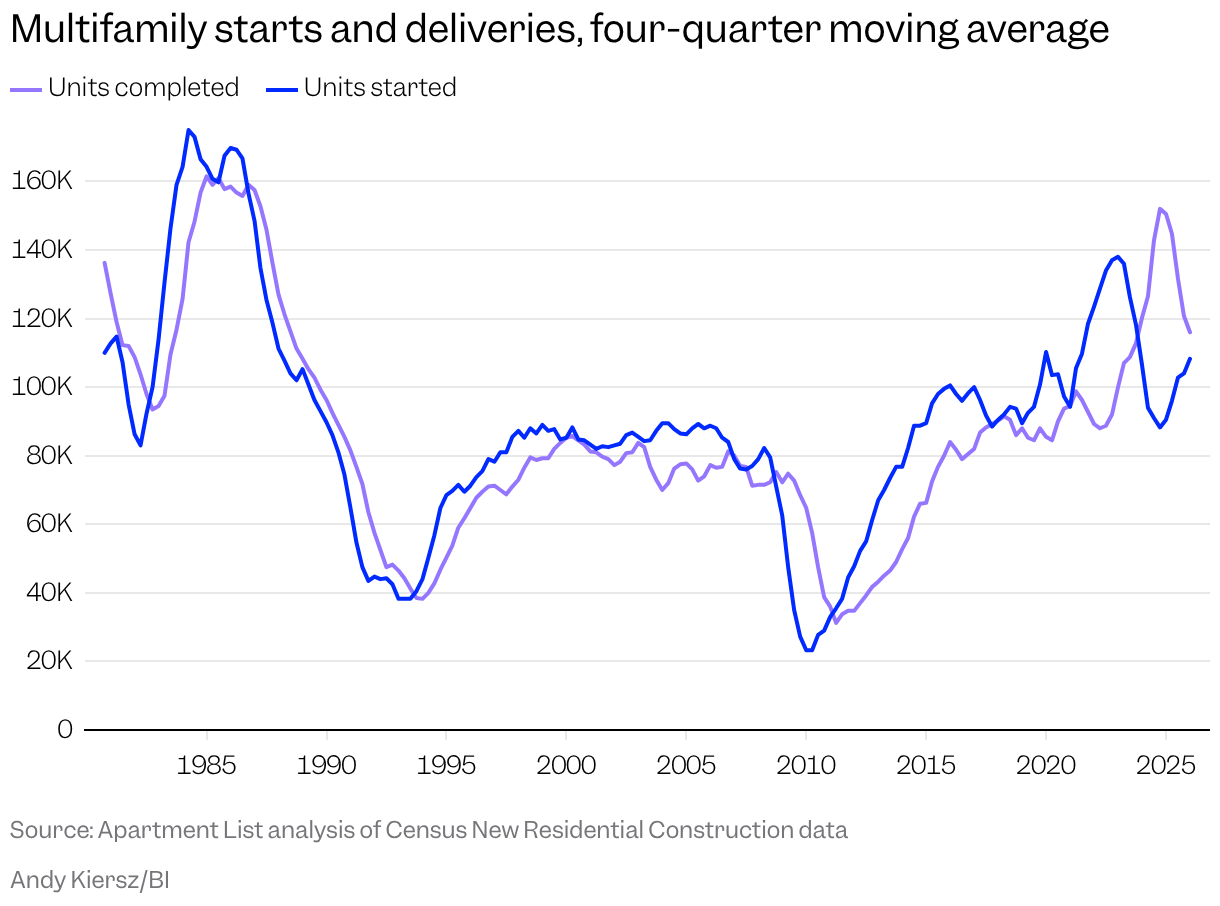
Apartment demand has held up better than expected, but it hasn’t been enough to keep up with the construction boom. People are no longer moving at the breakneck pace of 2021— given the rise in both home prices and rents, an anxiety-inducing job market, plus economic uncertainty around borrowing rates and inflation, many are choosing to stay put. Immigration to the US is way down, slowing population growth and hampering housing demand. A lack of new hiring also means fewer reasons for Americans to relocate, which, in turn, means less leasing traffic for property managers. A recent college graduate who might have happily rented a studio apartment may instead be forced to shack up with their parents while continuing their job hunt from home.
The ultimate result is that nationwide rents have either fallen or flatlined, depending on who you ask. Apartment List data shows the national median rent was down 1.7% from a year ago and 5% from its 2022 peak. RealPage found a more modest 0.4% year-over-year decrease in April, while Apartments.com, a subsidiary of the real estate giant CoStar Group, reported a slight 0.4% increase in average rents from a year prior (the company also noted, however, that setting aside 2020 weirdness, rent gains in April were the weakest since 2014). These companies are all working with their own datasets and use slightly different methods to calculate their results, hence the minor variance. But regardless of the source, analysts and property managers are reporting more concessions, flat renewals, and outright rent decreases. Apartments.com, for instance, found that roughly 41% of multifamily properties nationwide were offering rent concessions, an almost 10 percentage-point increase from a year ago.
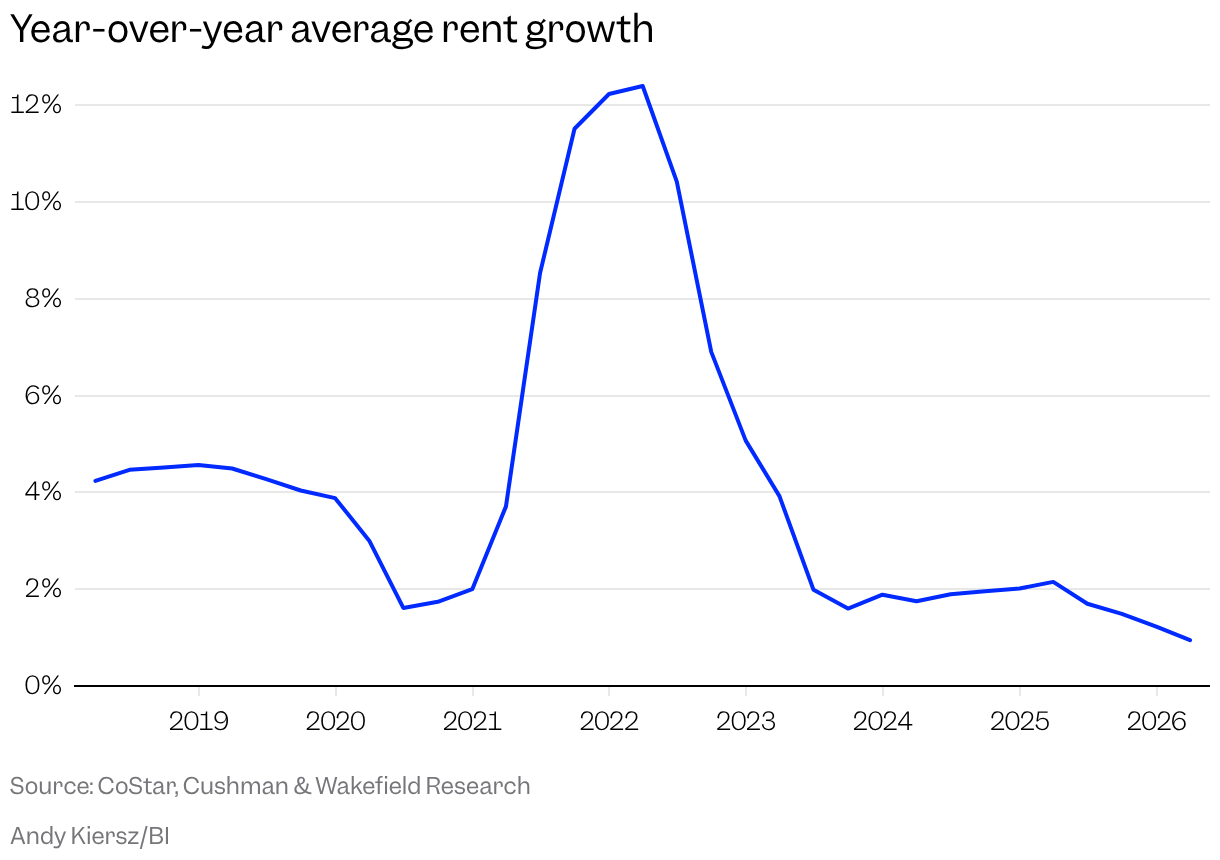
“For years, you’d post a vacancy, and you’d get a lease,” says Tony Julianelle, the CEO of Atlas Real Estate, which manages more than 6,000 units across 15 states. These days, however, “leasing is just harder.”
“If we’re break-even on rent growth right now, that’s something we should celebrate,” he adds.
The national numbers obscure some significant regional differences. Because builders focused so much of their efforts on the Sun Belt, those metros are seeing the biggest slowdown. In April, multifamily rents were down 2.2% year over year in the South and essentially flat in the West, RealPage found. The Midwest and Northeast, however, didn’t see the same construction boom: now rents are up 1.7% year over year in the Midwest and 1% in the Northeast.
If we’re break-even on rent growth right now, that’s something we should celebrate.Tony Julianelle, CEO of Atlas Real Estate
Some of the pandemic era’s star cities are now home to the biggest rent declines. Rents are down 6.5% year over year in Austin and 6.2% in Denver, with San Antonio, Tampa, and Phoenix rounding out the top-five metros with the deepest rent cuts, according to RealPage. If you’re bargain-hunting, keep an eye on Charlotte, Dallas, Las Vegas, and Raleigh, which have also posted significant year-over-year decreases.
In Denver, Kevin Tanner spent much of the past year trying in vain to find a tenant for his three-bedroom rental home in the Green Valley Ranch neighborhood, about 15 minutes from the airport. The previous tenants had been paying about $3,000 a month before they moved out last May. Tanner, who lives in Idaho, tells me he flew back to Colorado for a handful of tours over a few weekends, but returned each time with a still-empty property. Several dozen others started filling out applications, but never followed through. After the house sat vacant for almost half a year, he relented and hired a property management company, which advised slashing the rent by hundreds of dollars. In February, they finally secured a tenant at a monthly rent of $2,350 — almost $700 less than Tanner had been charging a year earlier.
“It’s a 100% loss when I’m not making any rental income,” says Tanner, who owns two other rentals and tells me he’s never had to lower the rent on any of his properties before. “My hands are kind of tied.”
Other landlords, hoping to dodge this exact scenario, are handing out bonuses to keep residents in place. One beneficiary is Ben Trepp, a 29-year-old who works for a government contractor and rents a one-bedroom in a large apartment building in Denver’s Lower Highlands neighborhood, right outside downtown. Last fall, he got the offer for his January lease renewal: no increase to his monthly rent. But Trepp had been keeping a close eye on the market and saw there were deals to be had elsewhere — heck, his own building was offering a month of free rent to new tenants. He responded to the property manager with an email outlining the prices at comparable units nearby. The property manager countered with a one-time $800 renewal bonus.
“They probably knew what they were going to offer before that,” Trepp tells me. “They just wanted to see if I was paying attention or not.”
Bario, the Maryland tenant who scored a rent cut of nearly $300 a month, may have a better grasp of the housing market than most: his company, Porch Swing Funding, deals in real estate debt. Bargaining down your rent doesn’t require an intimate knowledge of finance or a penchant for negotiations, however. Oftentimes, the “comps” — comparable rentals nearby — speak for themselves. After all, landlords across the spectrum also rely on cues from nearby properties to price their units. Much of this information is also readily available to the average renter via sites like Zillow or Apartments.com.
“Having that information was probably more helpful than I could have imagined,” says Neill, Bario’s wife.
A note of caution: If you threaten to leave unless your landlord cuts you a deal, be prepared to follow through. “Don’t be afraid to move,” Trepp tells me. “That’s your leverage.”
Landlords always fear leaving an apartment empty for an extended period. They may also be more willing to cut you a break because they’re wary of the costs of a “turn,” property-manager parlance for freshening up a unit for the next tenant. This process has never been more expensive, Julianelle tells me.
“The cost of paint has gone up. The cost of carpet has gone up,” Julianelle says. “All of that stuff is just more expensive.” A thorough turn for less than $1,500 “just doesn’t really exist anymore,” he adds.
Don’t be afraid to move. That’s your leverage.Ben Trepp, 29-year-old renter in Denver
Renters may have the upper hand for now, but their leverage is not long for this world. Walter, the researcher at the National Multifamily Housing Council, expects rent growth to be “fairly low this year,” but she says it could pick up a little next year as fewer new units hit the market. In the group’s most recent quarterly survey of the multifamily industry, a third of respondents said their expectations for construction starts this year had soured. The supply wave is undeniably receding: CoStar expects deliveries of new apartment units to drop by 55% this year, with a further decline in 2027. That said, this year’s delivery volume should still come in roughly in line with the past decade’s average, says Salviati, the economist at Apartment List.
“We’re past the peak of that boom,” Salviati tells me. “But it also hasn’t really fallen off a cliff by any means, either.”
Demand remains more of a question mark. Construction timelines are fairly easy to project, whereas the consumer psyche is subject to a vast range of economic forces. “Your forecast for demand is going to be as good as my forecast for demand, which is going to be as good as anyone else’s,” Sam Tenenbaum, the head of multifamily insights for Cushman & Wakefield, tells me. Things could change, in other words, and no one’s got the crystal ball. If demand holds up over the next couple of years, though, “it’s going to be much more landlord-friendly than it is tenant-friendly,” he adds.
Salviati says he’ll be keeping a close eye on the job market and inflation, the two factors that will play the biggest role in determining whether renters get footloose again. While the timing remains up in the air, he expects the market to eventually absorb the influx of units.
In the interim, renters are getting a welcome break from the usual housing-cost climb.
“You never hear of being able to go down in rent, right?” Neill tells me. “Historically, it just keeps going up and up, and there’s no room for negotiation.”
James Rodriguez is a correspondent on Business Insider’s Discourse team.
Business Insider’s Discourse stories provide perspectives on the day’s most pressing issues, informed by analysis, reporting, and expertise.
