
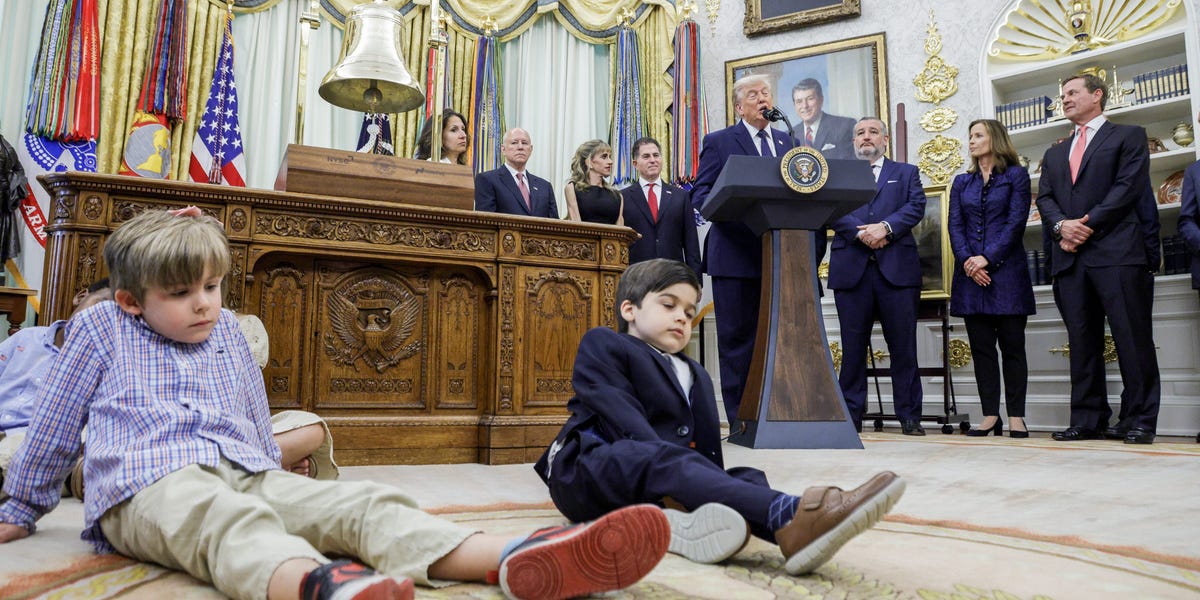
When Trump Accounts became available, Gene Goldman was on board.
The chief investment officer of Cetera Investment Management opened accounts for his twin girls, born earlier this year, giving each access to the $1,000 government contribution and a diversified stake in the market.
But now, the accounts he signed up for could look a little different.
The Treasury Department is now allowing companies and other donors to gift individual stocks to children’s Trump Accounts. What’s raised some eyebrows is that shares can’t be declined or sold for five years. Goldman said that changes the “character of the program” from a “simple, diversified vehicle” to one that could leave children with “single-stock exposure.”
There is still a lot of upside with a gifted stock, Goldman said.
“A child gets part ownership in a business at no cost, and it can grow tax-deferred for decades,” he said, potentially “adding up to a lot by adulthood.”
But many prickly issues and concerns could come up for parents, from taxes and investment risk to workplace compliance.
And, maybe most importantly, what can you do if you don’t want the stock?
After all, as part of the rollout of this new stock donation rule, the Treasury Department also opened new accounts for more than 60 million American children, without their parents needing to sign up. (Those born from 2025 to 2028 are eligible for the $1,000 government contribution, but their parents will still need to claim it.) The Treasury declined to comment for this story.
“This is the most generational thing we’ve done for youth,” IRS CEO and Social Security administrator Frank Bisignano said on CNBC Thursday, noting that donations already lined up range from “small to mega.”
Stock donations could make some children serious cash a couple of decades from now, but they are not free of considerations. Here’s what four financial planning experts said parents should know.
How and why does my child get gifted a stock in their Trump account?
Soon enough, there will be parents who find out that not only is their child a Trump Account holder, but their child owns some stock.
So how did the stock get there? It’s not as if donors like Gwynne Shotwell, SpaceX’s president, who pledged to donate $300 million in SpaceX stock, can just decide to place money in the accounts of specific children straight from their own personal accounts.
Donations can only come from a tax-exempt nonprofit, known as a 501(c)(3), a private foundation, or a donor-advised fund. It can target a group as small as 5,000 children based on characteristics such as ZIP code, family income, and age. The Treasury Department also needs to approve the donations, and, unsurprisingly, the donated stocks must be of American companies.
It’s not novel for individual donors to donate stocks to a charity, said Brian Boswell, senior wealth advisor from Savvy Advisors. It’s long been a way to give highly taxed shares to charity, deduct the full-market value as a charitable gift, and “never pay capital gains tax on the growth.”
Given the size of the donations, donors are likely to be quite wealthy and potentially rare. Boswell said he doesn’t expect to see the donations too often.
“It suits a small group of high-net-worth donors with large, low-basis public stock positions (founders and early employees after an IPO, for example) who already give through a foundation or donor-advised fund,” he told Business Insider.
What happens when you own the stock?
Once the stock is in the Trump account, it operates similarly to a traditional IRA. It continues to appreciate in value, and there are no tax considerations until money is withdrawn from the account.
There’s no way to decline the individual stock, and no way to sell until it’s been held for 5 years or the child holding the account turns 18.
For account holders whose parents work in industries like financial services, government, or journalism, which can have strict rules about stock ownership, this creates a new compliance headache.
Tim Steffen, director of advanced planning at Baird Private Wealth Management, has to follow strict rules with his own investments. With a few exceptions, like a spouse’s employer-based retirement plan or certain 529 college savings plans, his accounts have to be managed by his firm.
“An account that we’re investing in and managing that’s held away from our firm is not something that’s looked kindly on in general,” Steffen told Business Insider. Such rules prevent financial advisors from using the confidential information they learn in the course of their job to make money.
Don’t fret if you have to follow these rules; Steffen expects employers with strict compliance regimes to make Trump accounts another exception.
“Each employer and each industry is going to have to figure out how to address the individual stock issue,” Steffen said, especially as you have almost no control over these allocations.
When and how can I sell it?
As the rules are now, even if your child receives stock in a company you have an ideological or financial reason to oppose, you’re stuck with it.
The rules raise theoretical possibilities for influence or unwanted ownership. A company closing a factory could give stock to children in the surrounding community. A business trying to win support for a major local project could make nearby children shareholders. Or, more simply, a donor could give children shares in a company their parents might actively avoid, like a defense contractor or tobacco company.
The biggest financial risk here, Goldman said, is “putting too many eggs in one basket.”
“The best approach is to treat it as a bonus on top of a diversified core, not a replacement for one,” he said.
Christina Taylor, vice president of tax development and delivery at fintech company April, said that at the end of the holding period, the shares could be sold and the money can be put into a diversified vehicle, while “any gains from the holding period stay in the account to continue growing.”
“The child gets money they didn’t have before, with no tax due when it goes in and years of tax-deferred growth ahead,” she said.
As for tax implications, it’s very similar to an employer making a matching contribution to your 401(k), said Steffen. That means any money not put in by the family will be treated as income and will be fully taxable when withdrawn.
“If the only thing you ever have in the account is the $1,000 that you got from the federal government, or maybe one of these charitable gifts, then yes, every penny that comes out would be totally taxed,” Steffen said.
Just like IRAs, capital gains growth will likely be taxed as ordinary income when the money is withdrawn, said Taylor, with the same 10% penalty for early withdrawals before you’re close to retirement age.
The reality, though, says Taylor, is that all of this is subject to change, with Treasury still taking comments on the rule changes, which are also temporary and will expire in 2029. She expects more tweaks before it’s finalized, after all, we’re already far afield of the original pitch.
“Congress set these accounts up to hold diversified, low-cost index funds, so letting a donor pick an individual stock is a big departure from their original intent,” Taylor said.
